
Do you struggle with always having too much month left at the end of your money? You’re not alone. Here’s some stats on the current state of personal finances according to a Bankrate survey:
22–24% report no emergency savings at all.
47% say the couldn’t cover a $1,000 emergency;
Most shocking is a substantial minority have more credit-card debt than emergency savings.
That kind of financial pressure wears a man down.
Money problems affect more than a checking account. They put strain on a marriage, distract you at work, affect how you show up for your kids, and steal your peace of mind. There is nothing enjoyable about living one unexpected expense away from a crisis.
I know. I’ve been there.
When Susan and I were first married we had a dog named Sadie, a demonic schnauzer. Highly energetic and incredibly ill behaved.
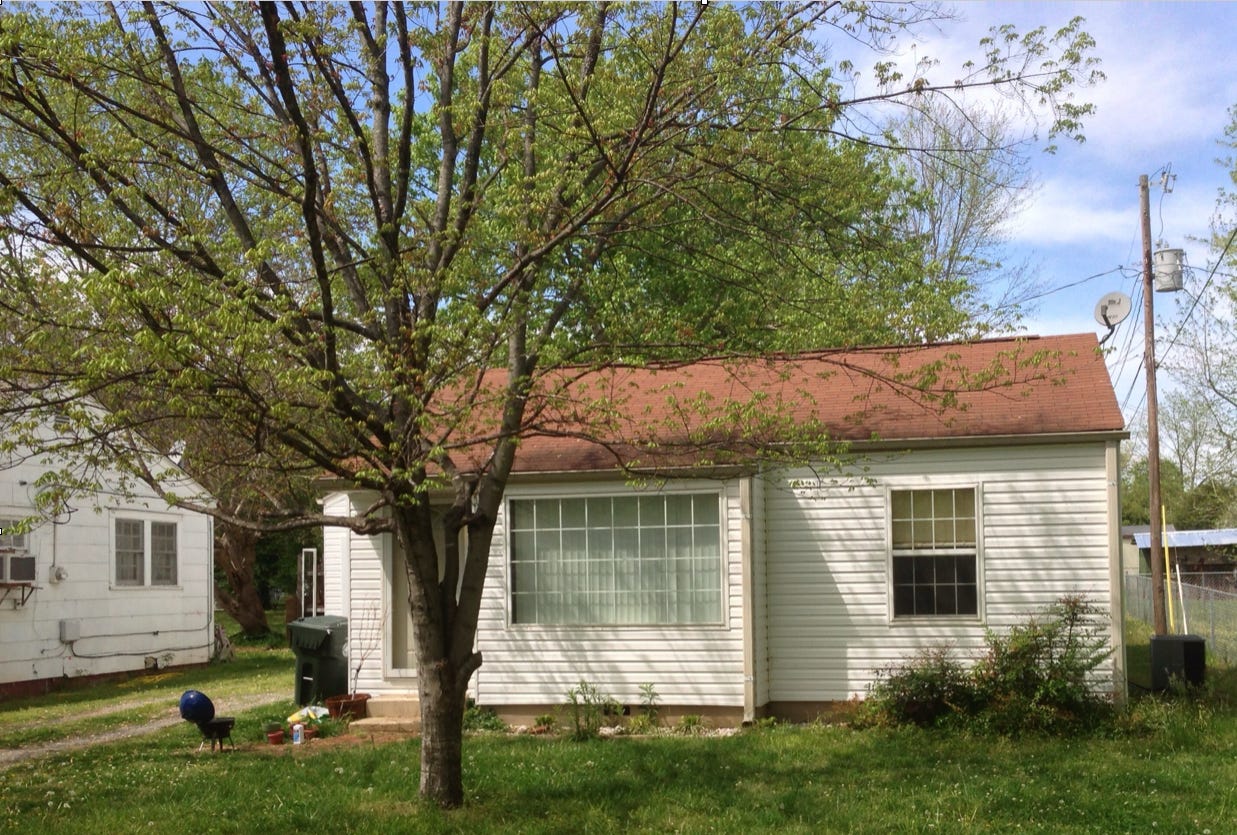
Susan, Sadie, and I lived in our first house pictured above. 832 sq ft of pure luxury. The bedroom we used was so small that we had to take the door off of the closet so we could use it and that’s where Susan kept her shoes.
One day we came home and Sadie the demonic schnauzer had eaten a brand new pair of Susan’s shoes. When she saw them, she sat on the edge of the bed and began to sob.
When I asked her what was wrong, she said “My shoes are ruined and we don’t have the money to buy another pair.”
That was a punch in the gut.
The truth was we were not broke because we were unemployed. We were broke because I was not managing our income well. We had money coming in, but we did not have a plan for where it was going.
I’d like to tell you we immediately changed how we handled our money, but that wouldn’t be true. Part of the reason was we didn’t know how. This was back in the mid 80’s when Dave Ramsey was busy going broke and hadn’t started teaching people how to manage money. We didn’t know you could come up with a plan to get out of a financial hole fairly quickly.
But I learned how and that’s why I’m writing this column.
You Don’t Have To Be “Good with Money”
Before you say “I’m not good with money”, let me tell you an uncomfortable truth; you don’t have to be a financial genius to manage your money. All you need is:
Basic math
Honesty about your situation
The discipline to follow a plan
Whether you use an excel spreadsheet, smart phone app or pencil and paper, there is only one equation you have to master so you can manage your money: You must Spend less than you Earn.
Simple? Yes.
Easy? Rarely.
The hard part is not the math. The hard part is the behavior.
One reason it’s difficult is because family budgets and behaviors have changed dramatically over the last 70 years. Especially when it comes to debt.
The first credit card, called Diner’s Club, appeared in 1950 and the only thing you could do with it was pay for meals at a limited number of restaurants. That’s it. But the idea caught on so fast credit cards like American Express, Visa and MasterCard popped up everywhere in a few years.
And the concept of consumer debt was born.
Can you imagine a world without credit cards? It’s hard, but I sure do wish I lived in that world. Lewis Grizzard said it best, “Credit cards are financial heroin”.
For a man carrying a balance from month to month, credit cards are not a convenience, it’s a weight. It’s a chain around his neck. It forces you to take money you could use for food, savings for your children, retirement, or generosity and instead send it to a credit card company.
BTW, the average credit card debt per household is $11,000!
Credit cards aren’t the only way family budgets have changed in the last 70 years.
Before World War II most mortgages were for 3 to 5 years for $7,000 on a house that was 983 square feet. Now mortgages are for 30 years for $300,000 on a house that is over 2500 sq ft.
Credit card and huge mortgages are examples of the root issue of our current financial condition; DEBT
Solomon knew about the dangers of debt when he taught his son: “Just as the rich rule the poor, so the borrower is servant to the lender. “(Proverbs 22:7 NLT)
That’s why the overarching financial goal of every man should be to eliminate all debt except your house.
Here’s how (thanks to the Dave Ramsey group for these suggestions):
1. Get mad enough to change
The steps some of you are going to have to take to get your financial house in order will require you to change your behavior so dramatically, the only way you’ll actually do it is to get mad about your finances. Behaviour changes like stop eating out, sell things, work extra hours or tell your family “not right now” on a purchase will make you feel like a failure. But guys, that is NOT failure. That is leadership.
2. Stop adding to the problem
Cut up your credit cards. Don’t freeze them in water. Don’t put them in your safety deposit box. Destroy them. We melted ours in the oven on a cookie sheet while our girls watched.
There is no good excuse to keep a credit card when you’re in financial distress because there is nothing you can do with a credit card that you can’t do with a debit card.
Why the drastic measure? The reason credit cards are so lethal to a man’s financial life is the amount of interest you pay on the balance.
Did you know it would take more than 13 years to pay off a $11,000 credit card balance if you only made the minimum payment (assuming an interest rate of 20% and a minimum payment of 2.5% of the balance)? And you will have paid a total of $21,000!
That is enough to wreck anybody’s financial peace of mind.
3. Give every one of your dollars a job
To do this, develop a spending plan, not a budget. The difference is a budget is static but a spending plan changes as needed because there are seasons of life. For example, Christmas and back to school shopping is always coming.
To do this, get out your toolbox:
Bills
Calendar (I use Google Calendar)
Calculator
Checkbook
Notebook
Bank Statement
Spreadsheet
The main point of this exercise is you’ll stop living on credit cards and start living on cash using the envelope system.
How It Works
Develop Your Plan: Create a monthly zero-based budget using apps or spreadsheet (email dee@deelauderdale.com and I’ll send you a template to help get you started) to assign every dollar a job before the month begins.
Withdraw Cash: Take out the exact amount of cash you budgeted for various spending categories (such as groceries, restaurants, clothing, fun money or vacation savings).
Stuff Envelopes: Put the cash into separate envelopes labeled with each category name.
Spend Only Cash: Pay for your purchases using only the cash inside the respective envelope. Once the cash is gone, your spending in that category stops for the month.
Handle Leftovers: Roll over or put any leftover cash at the end of the month toward your emergency fund or debt snowball
Why It Works
Physical Pain of Spending: Handing over physical cash triggers psychological “ouch” moments in the brain, helping curb impulse buying compared to the pain free act of swiping a debit or credit card.
Visual Tracking: You can see your progress at a glance; when an envelope gets thin, you naturally slow down your spending
Next Steps
Take your bills and put down the due dates on a calendar. Then check the calendar every day. Or do what I do and put them in Google Calendar with a reminder set for the day BEFORE it’s due.
Check your bank balance regularly.
Balance your checkbook monthly if old school.
CAUTION-If you don’t do this next step, you’re going to fail!
Accumulate a $2000 emergency fund. Keep it where you can get it but NOT in your normal checking account. Now you’re prepared when the washing machine breaks or the car needs tires. You won’t have to put it on a credit card, which would be like putting dirt back in the hole you just dug.
Once you’ve done all of this, now comes the fun part, attacking your debt!
Use the debt snowball to pay off debt.
List debts smallest → largest, ignoring interest rates.
Pay minimums on all debts.
Attack the smallest debt with all extra money.
Roll the freed up cash into the next-smallest debt once the first is paid off.
Repeat until all debts are eliminated.
BTW, the reason you go by the dollar amount more than the interest rate is you need to have victories in the beginning as motivation. Remember, the issue is not math, it’s behavior.
You’re going to be shocked at how quickly you can pay off what seems like an insurmountable debt load using these steps. Just stay focused and work your plan.
The word I want you to leave you with is MARGIN.
You need margin in every part of your life but especially in the area of your finances. Have a little bit of breathing room. That way you’re prepared for a disaster or a sudden opportunity to be generous.
Financial margin can remove a huge source of stress if you’re married, and that always pays nice dividends.
PS
This works! We’ve gone from being driven to tears by a demonic schnauzer to being debt free INCLUDING our house. And I have to say it’s a pretty good feeling to pull in the driveway in my paid for truck looking at my house that is paid for.
Especially as a grandfather.
I know that no matter what happens, my kids and grandkids will have a roof over their heads.